


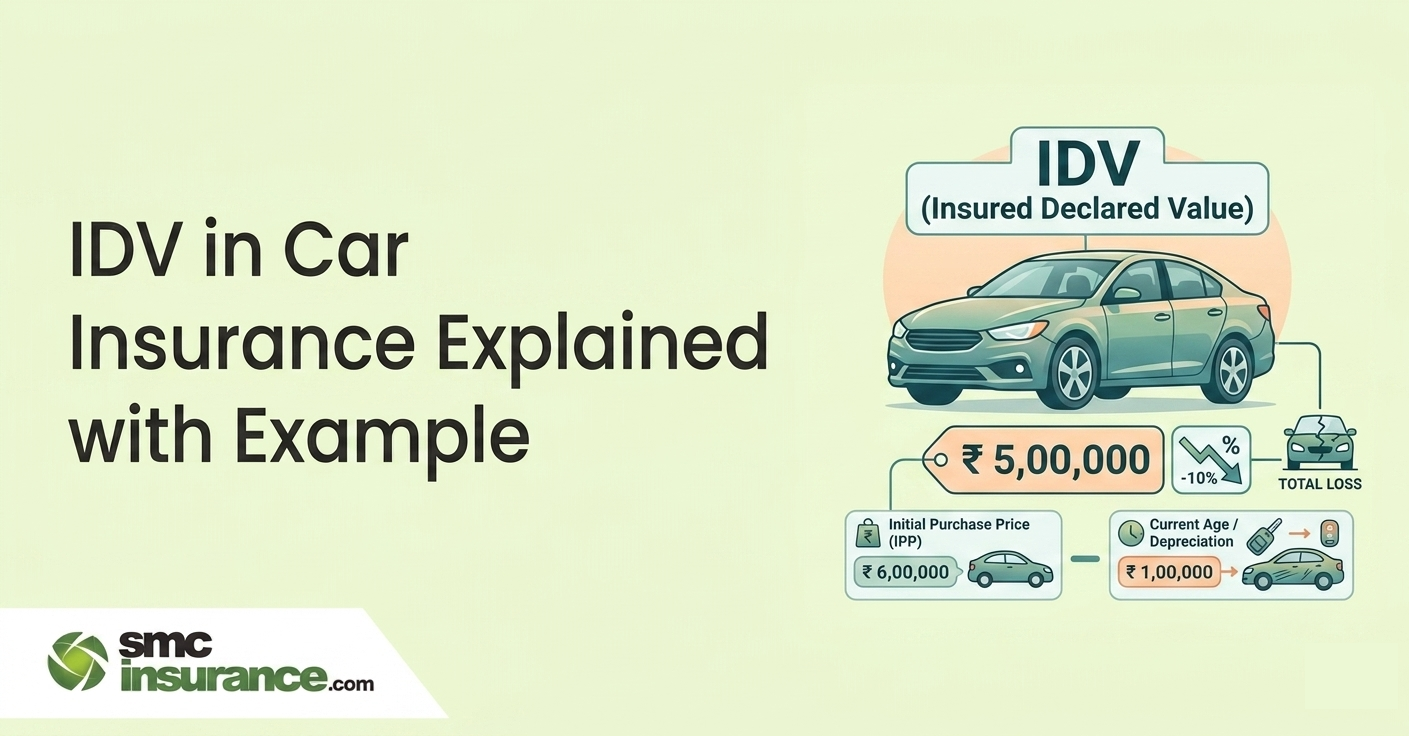
IDV (Insured Declared Value) is the maximum amount an insurer pays if your car is stolen or damaged beyond repair. It is built from the manufacturer's listed ex-showroom price, reduced by a standard age-based depreciation (5% for a car up to six months old, rising to 50% in its fifth year). Insurers apply this schedule, which comes from the India Motor Tariff and sits inside their IRDAI-filed policy wordings. For cars beyond 5 years, IDV is mutually agreed between insurer and policyholder. A higher IDV means a higher premium but greater claim protection. The right IDV should closely reflect your car's actual current market value, neither inflated nor deflated. Always verify your IDV at every renewal.
New for 2026: from 15 December 2026, IRDAI requires private car policies to be split into four sections, and the section that covers your own vehicle (the one that uses IDV) becomes a separate, optional layer. Check the option form carefully before you decline it.
You renew your car insurance every year. You pay the premium . And somewhere in the policy document, there's a number called IDV — Insured Declared Value. Most people skip right past it. Then their car gets stolen or totalled and they discover it was that one number that decided how much they actually received. Not the premium they paid. Not the brand of the insurer. Just the IDV.
Understanding IDV in car insurance is not complicated. But getting it wrong (either too high or too low) has very real financial consequences. This article explains what IDV means, how it's calculated using IRDAI's official depreciation schedule, how it affects your premium and what you should actually do at renewal time.
What IDV in Car Insurance Actually Means
IDV stands for Insured Declared Value. It is the maximum amount your insurer will pay you if your car is stolen or damaged beyond repair - what the industry calls a total loss or constructive total loss (CTL).
IDV represents a standardised estimate of your car’s current market value, calculated using depreciation norms defined by IRDAI. It is not the price you paid at the showroom. It is not the on-road price. It is calculated based on the manufacturer’s listed selling price of the vehicle (excluding registration and insurance costs), adjusted for depreciation as per IRDAI guidelines.
The Official Definition from IRDAI
In the standard private car package wording, the IDV is treated as the sum insured. It is fixed when each policy period begins and, for total loss, constructive total loss and cash loss claims, it is regarded as the vehicle's market value for the whole period with no further depreciation. One nuance: on multi-year own-damage products, some insurers' wordings reset IDV at each one-year block using the same depreciation grid, so read the schedule of a long-term policy before assuming a single flat IDV.
A car is declared a constructive total loss when the cost of repair exceeds 75% of its IDV. In total loss or constructive total loss claims, the insurer pays the IDV. If the policyholder retains the salvage, its value is deducted from the payout.
What IDV Does Not Cover?
IDV matters only where your own vehicle is insured, meaning a package (comprehensive) policy or a standalone own-damage policy. A pure third-party policy has no IDV, because it pays for harm to others, not for your car. If you hold only a third-party policy — which covers damage you cause to others — IDV does not apply. For partial damage claims (dents, broken windshields, minor accidents), the insurer pays actual repair costs, not the IDV. However, the cut applied to replaced parts depends on the material.
- Rubber, nylon and plastic parts, tyres, batteries and airbags carry a 50% deduction
- Fibre-glass components 30%
- For glass, nil
- Paint is depreciated at 50% on its material cost only and where a garage issues one consolidated paint bill, a quarter of that bill is treated as material.
All other parts follow an age-based grid that starts at nil for a car up to six months old and climbs to 35% in the fifth year, 40% between five & ten years and 50% beyond ten years. Individual insurers can differ, so check your own policy wording.
What Changes from 15 December 2026: The Four-Layer Motor Policy
IRDAI has told general insurers (health-only and specialised insurers excluded) to sell private car and two-wheeler cover in four distinct layers, using uniform policy wording, a customer option form and an information sheet. The rules apply to every policy issued on or after 15 December 2026.
Layer |
What it covers |
Status |
Section I |
Liability to third parties |
Compulsory |
Section II |
Legal liability to occupants or pillion riders |
Optional |
Section III |
Personal accident: owner-insured (compulsory); occupants/pillion riders (optional) |
Mixed |
Section IV |
Loss of or damage to your own vehicle |
Optional |
Where does IDV come in? Only in Section IV. If you skip that layer, you have no IDV and no claim for theft, flood or accident damage to your own car. Insurers remain free to design and price own-damage cover, provided the four-layer structure stays intact, and they must show the cover and premium for each section separately on your policy schedule. If you already hold a policy, you can add Section II mid-term through the insurer that issued your third-party policy, by paying extra premium, without cancelling anything.
The change comes from the Supreme Court's directions in National Insurance Co. Ltd. v. Smt. Thungala Dhana Laxmi and is also meant to make the products visible on the Bima Sugam platform.
How IDV Is Calculated: The IRDAI Depreciation Schedule
Every insurer in India uses the same depreciation schedule laid down by IRDAI to calculate IDV. Here's the formula:
IDV = Manufacturer's Listed Ex-Showroom Price − Depreciation Value |
If your car has non-standard accessories (alloy wheels, upgraded music system, aftermarket additions), their declared value, subject to depreciation and acceptance by the insurer, is added separately to the IDV.
IRDAI's Official Age-Wise Depreciation Table for IDV
Age of the Vehicle |
Depreciation Rate for IDV |
Up to 6 months |
5% |
6 months to 1 year |
15% |
1 year to 2 years |
20% |
2 years to 3 years |
30% |
3 years to 4 years |
40% |
4 years to 5 years |
50% |
Above 5 years |
Mutual agreement between insurer and insured |
Source: IRDAI Standard Motor Insurance Policy Wording. For vehicles older than 5 years and discontinued models, IDV is determined by mutual agreement between the insurer and the policyholder — often based on market surveys or third-party valuation tools.
Worked Example: A 3-Year-Old Maruti Suzuki Baleno
Say you bought a hatchback two and a half years ago, with a manufacturer's listed ex-showroom price of Rs. 8,00,000 (a round figure used only for illustration). It is in the 2-to-3-year bracket, which carries 30% depreciation.
- Depreciation value: 30% of Rs. 8,00,000 = Rs. 2,40,000
- IDV = Rs. 8,00,000 − Rs. 2,40,000 = Rs. 5,60,000
If you have declared accessories worth Rs. 30,000 (with their own 30% depreciation applied):
- Accessories after depreciation: Rs. 30,000 − Rs. 9,000 = Rs. 21,000
- Total IDV = Rs. 5,60,000 + Rs. 21,000 = Rs. 5,81,000
This Rs. 5,81,000 is the ceiling on what your insurer pays if the car is stolen or written off. Not a rupee more.
How IDV Affects Your Car Insurance Premium?
This is where many policyholders make a mistake - deliberately!
Your car insurance own-damage (OD) premium is calculated as a percentage of IDV. The higher the IDV, the higher the premium. This leads some people to declare a lower IDV just to reduce what they pay annually. Saving Rs. 1,500–Rs. 2,500 on premium sounds reasonable until the car is totaled and the claim comes in far short of replacing it.
IDV vs. Premium
To see how IDV drives cost, assume, purely for illustration, an own-damage rate of 2.2% of IDV before discounts. Real rates vary by insurer, city, engine capacity, add-ons and No Claim Bonus.
IDV declared |
Illustrative OD premium (2.2%) |
With 18% GST |
Maximum total-loss claim |
Rs. 4,00,000 |
Rs. 8,800 |
Rs. 10,384 |
Up to Rs. 4,00,000 |
Rs. 5,00,000 |
Rs. 11,000 |
Rs. 12,980 |
Up to Rs. 5,00,000 |
Rs. 6,00,000 |
Rs. 13,200 |
Rs. 15,576 |
Up to Rs. 6,00,000 |
Note: OD premium rates vary by insurer, city, engine capacity, NCB (No Claim Bonus) and add-ons chosen. The above is illustrative, not a quote. Actual premiums must be verified with your insurer.
The Rs. 2,000 you save annually by undervaluing IDV can cost you Rs. 1,00,000 or more at claim time. That's not a trade-off; it's a trap.
Pushing IDV far above what the car would fetch in the used market does not buy you more safety. You pay a larger premium every year, and the policy still treats IDV as the ceiling, not a guaranteed payout, so a payout never exceeds what the loss actually justifies under the policy terms. Declare what the car is realistically worth, and keep your disclosures about condition and accessories accurate. For own-damage cover, insurers determine premiums based on multiple factors including IDV, vehicle age and claim history and may charge different rates for similar coverage as permitted under IRDAI guidelines.
IDV, GST and What You Actually Pay
GST on motor insurance remains 18%, and it is charged on the full premium, including add-ons. The September 2025 GST Council relief covered only individual life and health policies, not motor. A private car owner cannot claim the GST back as input credit; that benefit is restricted to specific business uses of vehicles. Claim payouts themselves do not attract GST.
So a Rs. 11,000 own-damage premium becomes Rs. 12,980 at checkout (Rs. 11,000 + Rs. 1,980).
The Right IDV: Neither Low Nor High
The ideal IDV is one that closely reflects your car's real current market value. For new cars up to 5 years old, the IRDAI depreciation schedule takes care of this automatically — just ensure your insurer is using the correct ex-showroom price for your vehicle's make, variant and city.
For cars older than 5 years, the IDV is negotiated. This is where you need to do some homework. Check used car platforms for your make, model and year to get a sense of actual resale value. Don't let the insurer default to the lowest number; don't push for an unrealistically high figure either.
Renewal Checklist: Is Your IDV Right?
- Find the IDV on your renewal quote, not just the premium.
- Work out the car's age band, then multiply the listed ex-showroom price by the retained share (95%, 85%, 80%, 70%, 60% or 50%).
- Add the depreciated value of declared accessories.
- If the car is past five years, compare with used-car listings for the same make, model, year and city.
- Ask the insurer to explain any gap larger than your own working shows.
- If you are switching insurers, confirm the new quote uses the same reference price.
When You Should Consider Adjusting IDV?
Situation |
What to Do |
Car is in excellent condition for its age |
Negotiate a slightly higher IDV with your insurer |
Car has high mileage, visible wear |
Accept standard or lower IDV to keep premium reasonable |
Car is more than 5 years old |
Compare market resale prices and fix IDV accordingly |
Car has aftermarket accessories |
Declare them separately; their depreciated value adds to IDV |
Switching insurers at renewal |
Confirm the new insurer uses the same ex-showroom reference price |
Note: Insisting on IDV significantly above actual market value will likely cause disputes at claim settlement. Insurers may assess actual market value independently during a total loss claim.
Not sure what IDV your car currently carries — or whether it's the right number? Comparing policies side-by-side before renewal makes sense. Visit SMC Insurance to check plans, compare IDV options and buy car insurance with the right coverage for your vehicle's current value.
IDV at Claim Time: What Actually Happens
Setting the right IDV is only half the picture. Understanding how it applies during a claim is the other half.
For total loss, constructive total loss and theft: The insurer's liability is capped at the IDV. The compulsory deductible applies to every event, including one that ends in a total loss: Rs. 1,000 for private cars up to 1,500 cc and Rs. 2,000 above that. On a standalone own-damage policy, the same thresholds are applied by engine size, and for electric cars by motor power, with 65 kW as the dividing line. If you choose to keep the damaged vehicle, its assessed wreck value is subtracted from what you receive; if the insurer takes the wreck, nothing is subtracted for it.
For partial damage claims: IDV is the upper cap — but the actual payout is the cost of repairs, subject to depreciation on replaced parts (unless you hold a zero-depreciation add-on). The insurer won't pay more than the IDV even for repairs, but in practice, partial claims rarely approach IDV.
CTL threshold: A car becomes a constructive total loss when the combined cost of retrieving and repairing it exceeds 75% of its IDV. The insurer then settles at IDV (less wreck value if you keep the vehicle, and less the deductible) and you will be asked to surrender the registration certificate for cancellation.
Total Loss Payout: A Worked Example
Suppose your total IDV is Rs. 5,81,000 and the car is under 1,500 cc.
- Insurer's maximum liability: Rs. 5,81,000
- Less compulsory deductible: Rs. 1,000 to Rs. 5,80,000
- If you keep the wreck and it is assessed at Rs. 40,000 to Rs. 5,40,000
- If the insurer takes the wreck to Rs. 5,80,000
Any voluntary deductible you opted for would reduce this further.
Summing Up,
IDV in car insurance is not a formality. It's the financial foundation of your own-damage coverage. Every claim scenario (theft, flood, accident write-off) resolves to this single number. The IRDAI has fixed clear depreciation rates to ensure uniformity across all insurers, but the responsibility of checking and confirming your IDV at each renewal falls on you.
Don't let renewal become a routine where you just click "renew" and move on. Spend two minutes confirming that your IDV matches your car's actual market value. If your car is older than 5 years, invest a little more time comparing resale prices before accepting whatever your insurer proposes. And if you've added accessories after purchase, declare them — their depreciated value increases your IDV and your claim protection. The right IDV costs you a fair premium and pays you a fair claim. That's the deal.
Disclaimer
The information provided on this platform is intended for general awareness and educational purposes. While every effort is made to ensure accuracy, some details may change with policy updates, regulatory revisions, or insurer-specific modifications. Readers should verify current terms and conditions directly with relevant insurers or through professional consultation before making any decision.
All views and analyses presented are based on publicly available data, internal research and other sources considered reliable at the time of writing. These do not constitute professional advice, recommendations, or guarantees of any product’s performance. Readers are encouraged to assess the information independently and seek qualified guidance suited to their individual requirements. Customers are advised to review official sales brochures, policy documents and disclosures before proceeding with any purchase or commitment.
FAQs
IDV stands for Insured Declared Value. It is the maximum amount your insurer will pay you if your car is stolen or declared a total loss. It is calculated by deducting IRDAI-mandated depreciation from your car's ex-showroom price. IDV matters because it directly determines your claim payout and not what you paid for the car, not what it costs to replace it new, but the current assessed market value. Getting the IDV right at renewal ensures you're neither overpaying on premium nor underprotected at claim time.
For a car between 4 and 5 years old, IRDAI’s standard depreciation schedule applies a 50% rate. So if your car's ex-showroom price was Rs. 10,00,000, the IDV would be Rs. 10,00,000 minus 50%, which equals Rs. 5,00,000. Any declared accessories not included in the original manufacturer's price are also depreciated and added separately. This is the figure that appears in your policy schedule and determines your total loss claim ceiling.
Yes, within what your insurer agrees to. The standard wording lets the formula-based IDV be nudged up or down by agreement, and the factors it names include location, how the car is used and road or terrain conditions. There is no single regulator-published percentage band that I could confirm, so ask your insurer how far it will move and put the agreed figure in writing on the policy schedule.
For vehicles beyond 5 years of age, IRDAI does not prescribe a fixed depreciation rate. Instead, the IDV is determined by mutual agreement between the insurer and the policyholder. In practice, insurers may refer to used car valuations, third-party tools, or surveyor assessments. As a policyholder, you should check current resale prices for your make, model, year and city on established used car platforms before accepting the IDV your insurer proposes.
No. Third-party premiums are notified rates tied to vehicle type and engine capacity (the Ministry of Road Transport and Highways notifies them, with IRDAI's inputs), so they do not move with IDV. For private cars the annual base rates currently quoted by insurers are Rs. 2,094 up to 1,000 cc, Rs. 3,416 for 1,000–1,500 cc and Rs. 7,897 above 1,500 cc, with 18% GST added. A proposal to raise these was reported during 2025–26; check the latest notification on the day you buy.
IDV is the base value used to calculate claim payouts. In standard comprehensive policies, depreciation is deducted on replaced parts during partial damage claims — meaning you bear a portion of the repair cost. A zero-depreciation add-on (also called nil-dep or bumper-to-bumper cover) waives this depreciation on parts, so the insurer pays the full cost of replacement parts without deductions. Zero-depreciation does not change your IDV; it changes how depreciation applies to parts during partial claims. Both concepts are important but serve different purposes.
Yes, since IDV is based on the current ex-showroom price of your model and your car's age-based depreciation, it changes every year. A policy renewed without checking can carry a stale IDV — either too high (leading to unnecessary premium) or too low (leading to a shortfall at claim time). Make it a habit to verify the IDV shown at renewal and cross-check it against the depreciation schedule before accepting the policy.
The circular I read restructures the policy into four layers and standardises the wording, but does not itself state a new IDV formula. IDV still belongs to the own-damage layer. Check Section IV of your insurer's new wording once it is published.
No, it is an optional layer. Third-party liability and owner-insured personal accident remain compulsory. Skipping own-damage means no cover for damage to or theft of your own car.
Neither. GST at 18% is charged on the premium. Claim payments do not carry GST.
Yes, it applies to every event, including one that ends in a total loss or constructive total loss.


