


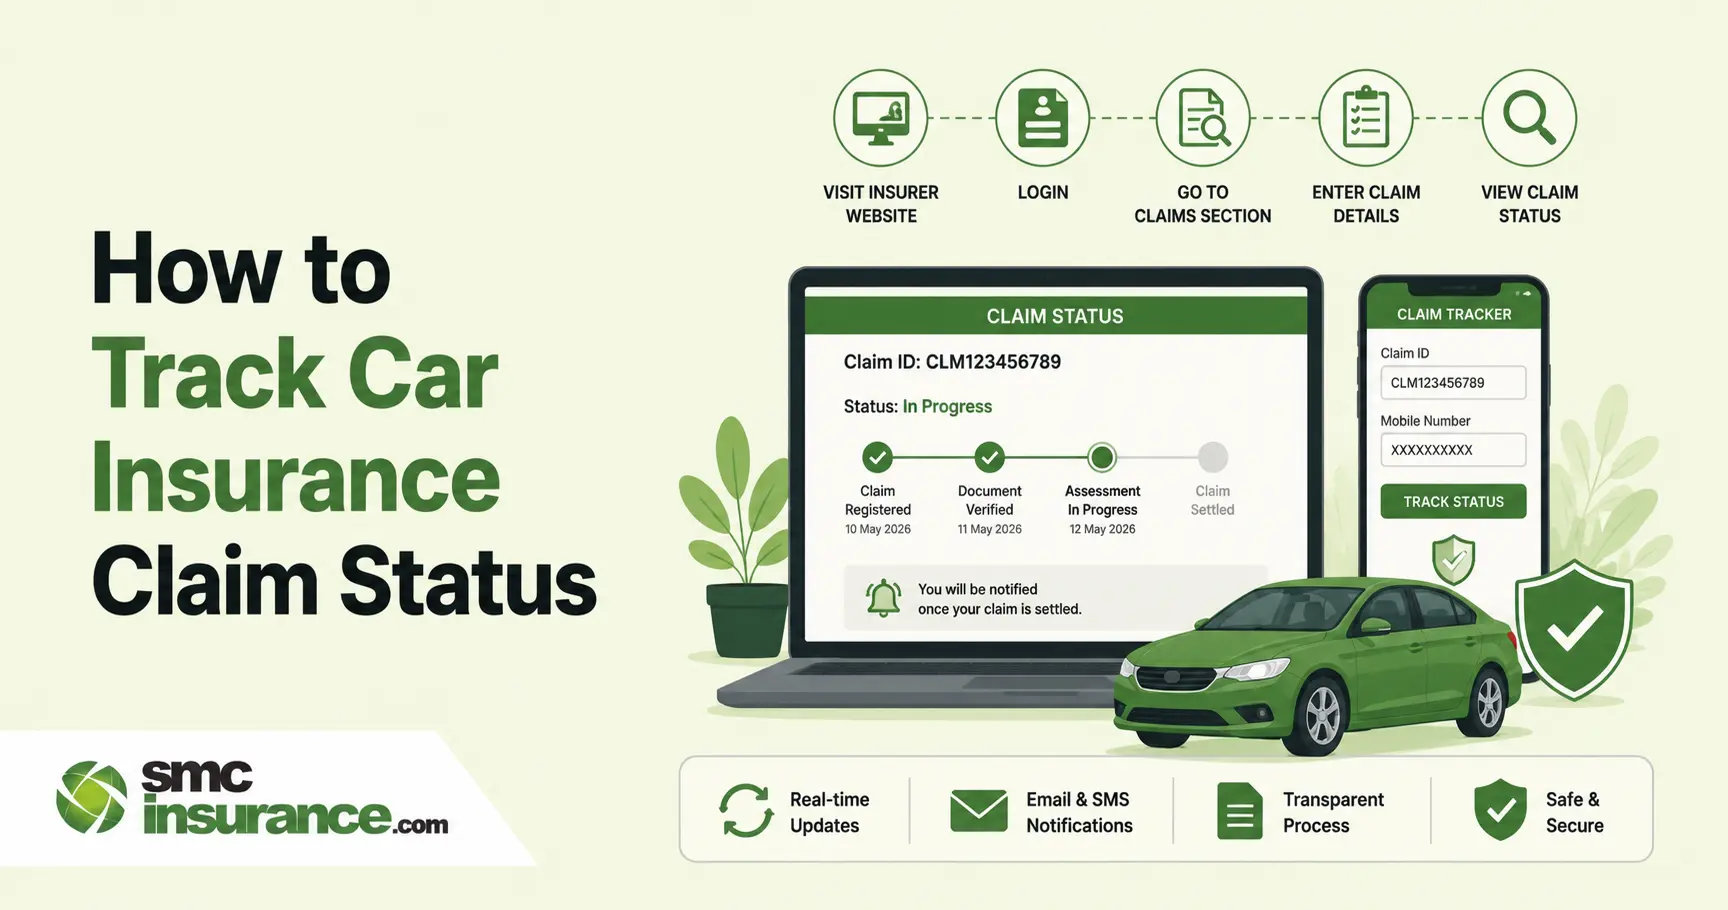
You can check your car insurance claim status on your insurer's website or app using the claim number, policy number or registered mobile with an OTP, or through its official WhatsApp service or customer care. Under IRDAI's September 2024 Master Circular, a surveyor must be allotted within 24 hours of the claim being reported and the survey report must be submitted within 15 days of allocation. The insurer must decide the claim within 7 days of receiving the report or after 15 days from allocation, whichever is earlier. If the claim is not settled within the prescribed timeline, the claimant is entitled to interest at 2% above the bank rate. If the file stalls, escalate to the insurer's grievance officer, then Bima Bharosa (155255), then the Insurance Ombudsman.
Table of Contents
- Details You Need Before You Track Your Car Insurance Claim Status
- How to Check Motor Insurance Claim Status Online Through the Website, App and WhatsApp
- What Each Car Insurance Claim Status Means and What to Do Next
- How Long Should a Car Insurance Claim Take? IRDAI Turnaround Times for Motor Claims
- Why the Approved Amount May Be Lower Than Your Repair Bill: Deductible, Depreciation and NCB
- Car Insurance Claim Status Not Updating? Common Reasons and Fixes
- How to Escalate a Delayed or Rejected Car Insurance Claim: Grievance Officer, Bima Bharosa and Ombudsman
You registered the claim on Monday and got a claim number by SMS within minutes. By Thursday the car is still at the garage, the service advisor says the approval is "pending with the insurer" and the helpline tells you the file is "under process", which explains nothing. Every extra day costs you a cab fare or a rental and not knowing whether the delay is normal makes it feel worse than it is. Checking your car insurance claim status takes a couple of minutes once you have the right details and the right channel, but reading what the status means is what decides whether you wait or push. This guide covers both, along with the IRDAI deadlines your insurer is bound by and the escalation route if it misses them.
Details You Need Before You Track Your Car Insurance Claim Status
Lookups usually fail over small things like a mistyped character or an old phone number, so it pays to sort the basics first.
Your claim reference number is the key. It reaches you by SMS or email the moment the claim is registered and some insurers call it a claim intimation number or file number. The policy number and vehicle registration number work as backups. The mobile number linked to the policy matters more than most people expect, because that is where the login OTP goes, so update it before you need it. Type the registration number carefully too, since a letter O in place of a zero is enough to return an empty result and at least one large insurer warns about this on its own claim page.
Lost the claim number? Check your SMS and spam folder first. Failing that, your policy number and the accident date are usually enough for customer care to find the file. The network garage will also have the number on its approval request, so a call to the service desk is a decent fallback.
How to Check Motor Insurance Claim Status Online Through the Website, App and WhatsApp
There are four routes and the quickest depends on how your insurer has set things up.
- Insurer's website or app
Look under the claims menu for an option like "track claim" or "claim status". Depending on the insurer, you enter the claim number, policy number or registered mobile, then confirm with an OTP. The app often gives the fuller picture because pending document requests appear there and you can upload the file on the spot. - WhatsApp
Several insurers now run claim services on WhatsApp, where a greeting to the official number opens a menu with a claim-status option. Copy that number from the insurer's own website or your policy email, never from a search result, because IRDAI regularly cautions policyholders about spurious callers and fake helplines. - Customer care
Call or email with the claim number and ask three things: the current status, the specific item pending and the name of the person handling your file. Note the date and time of every conversation, because that log becomes useful evidence later. - Surveyor and garage
The SMS that assigns a surveyor typically carries their contact number. In a cashless claim, the garage sends its repair estimate to the insurer for approval, so the service advisor often knows where things stand before the portal does.
Some insurers let you search with the vehicle registration number alone, while others insist on the claim or policy number, so try whichever the page offers first. If you are still deciding how to get the car repaired, our explainer on cashless and reimbursement claims in car insurance shows how each route changes who you end up chasing.
What Each Car Insurance Claim Status Means and What to Do Next
Labels differ between insurers, but the journey underneath is the same, so use the table below to translate whatever your screen says.
Status you see |
What it usually means |
Your move |
Claim registered | Incident logged and claim number issued | Upload photos, RC, licence and policy copy today; hold non-urgent repairs until the surveyor has seen the car |
Documents pending | A query is open or a file is missing or unreadable | Reply the same day, since an unanswered query is among the commonest reasons a file sits idle |
Surveyor assigned | A licensed surveyor has been allotted to assess the loss | Expect contact within 24 hours of reporting; chase the insurer if nobody calls |
Survey done / under assessment | Surveyor is preparing the loss assessment report | Ask when the report was submitted, since 15 days from appointment is the outer limit |
Estimate approved | Insurer has accepted the garage's estimate (cashless) | Ask the garage what your share will be (deductible and depreciation) before work begins |
Supplementary estimate | Extra damage surfaced once the car was opened up | Normal; make sure the revised estimate is approved before the garage continues |
Approved / settled | Payment released to the garage or your bank account | Match the amount with the assessment before signing the satisfaction voucher |
Rejected / repudiated | Claim declined | Ask for the reason in writing and move to the escalation steps further down |
Total loss | Repair cost too high to justify repairing | Settlement is generally based on IDV, less deductible and salvage value, so check the IDV on your policy |
Note: Status names vary between insurers, so treat this as a translation guide and confirm anything unclear with your insurer in writing.
This is why a bare "under process" should never be accepted as an answer. Ask what the file is waiting for and since which date, because a handler who can answer both has actually opened your file. Since so much of the table hinges on the survey stage, our guide to car insurance claim inspection explains what a surveyor checks and why.
How Long Should a Car Insurance Claim Take? IRDAI Turnaround Times for Motor Claims
The clocks were tightened considerably in 2024, so older figures you may have read elsewhere are now out of date.
Under IRDAI's Master Circular on Protection of Policyholders' Interests, issued in September 2024, an insurer must allot a surveyor within 24 hours of a claim being reported. The surveyor then has 15 days from appointment to file the final report and the insurer must pay or reject within 7 days of receiving it.
Stage |
Earlier limit |
Current limit |
Surveyor appointed | 72 hours from intimation | 24 hours from claim being reported |
Final survey report filed | 30 days from appointment | 15 days from appointment |
Insurer pays or rejects | 30 days from survey report | 7 days from survey report |
Note: These limits apply to retail claims where a surveyor is appointed and assume you have submitted every document asked for. A registered surveyor is mandatory for motor losses above Rs. 50,000, while smaller claims follow the insurer's board-approved claims policy, so ask for its timeline in writing. Theft and total-loss claims involve police and salvage formalities and often run longer.
Put three dates in your phone: when you reported the claim, when the surveyor was allotted and when the survey report went in. If the 24-hour or 7-day limit is crossed, you have a documented breach to cite and the insurer is liable for interest at 2% above the prevailing bank rate on the delayed payment.
Why the Approved Amount May Be Lower Than Your Repair Bill: Deductible, Depreciation and NCB
Plenty of disputes that look like delays or rejections are really surprise deductions and you can see most of them coming.
Every own-damage claim carries a compulsory deductible, which is Rs. 1,000 for private cars up to 1500cc and Rs. 2,000 above that and any voluntary deductible you choose at purchase is added on top. Without a zero depreciation add-on, replaced parts are also depreciated and plastic, rubber and nylon components are commonly cut by 50%. A Rs. 20,000 bumper replacement can therefore leave roughly Rs. 10,000 on your side before the deductible even comes into play.
Then there is the no claim bonus. An own-damage claim generally resets your NCB at the next renewal, whereas a claim only for third-party liability usually leaves it alone. If the assessed damage sits only slightly above your deductible, paying yourself and keeping the bonus often works out cheaper, though the math depends on your NCB slab. Our walkthrough of an own damage claim shows where each deduction appears.
Tired of making the follow-up calls yourself? Chasing an insurer between meetings is a job in itself. If your policy is with SMC Insurance, or you are due to renew, our team can help you follow the claim file so you are not the one on hold. Start at SMC Insurance.
Car Insurance Claim Status Not Updating? Common Reasons and Fixes
When the status freezes for more than a few days, the cause is usually one of five things and only some of them sit with the insurer.
- A document request you never saw: Insurer emails land in spam and the portal's pending-documents tab can show a query the SMS never mentioned. Check both and upload the same day.
- Survey not completed: A surveyor who cannot reach you or the garage will stall the whole chain, so keep your phone reachable and tell the insurer exactly where the car is.
- A revised estimate: Hidden damage found during dismantling sends the file back for a fresh approval, which adds days.
- Parts in order: The status may read "repair in progress" while the garage simply waits for a part, which is a workshop delay rather than an insurer one. Ask for an expected date in writing.
- A discrepancy under review: Late intimation, a licence detail that does not match, or a policy lapse date close to the incident invites closer checks, so answer plainly and completely.
Whatever the cause, ask for it by email. A paper trail costs you nothing now and matters a great deal if you have to escalate.
How to Escalate a Delayed or Rejected Car Insurance Claim: Grievance Officer, Bima Bharosa and Ombudsman
If the deadlines above have passed with no result, the escalation path is free and moves in a fixed order.
- Insurer's grievance redressal officer (GRO)
Email the GRO with your claim number, the dates from your log, the deadline that was missed and the outcome you want. Under the 2024 framework, the insurer must acknowledge a complaint immediately and resolve it within 14 days. GRO details are published on the insurer's website. - Bima Bharosa
Register at bimabharosa.irdai.gov.in or call 155255 or 1800 4254 732. The complaint is forwarded to your insurer and if it is not attended to within 15 days, or the resolution is unsatisfactory, you can approach the Insurance Ombudsman. The portal never asks for payment and IRDAI specifically warns against scanning QR codes offering disbursements. - Insurance Ombudsman
Once the insurer's reply is unsatisfactory, or a month passes with no reply, file with the ombudsman office covering your area (cioins.co.in lists them). The complaint must be made within one year and it cannot be entertained if the same matter is already before a court or consumer forum. An award binds the insurer, which must comply within 30 days or pay Rs. 5,000 for each day of delay, on top of any penal interest.
Attach the policy copy, claim number, all correspondence and any rejection letter with each complaint.
Summing Up,
Tracking a claim is easy once you know where to look and the harder skill is knowing whether the status you see is normal. Keep your claim number and registered mobile handy, check the insurer's app or WhatsApp service first and use the garage as a second source when the repair is cashless. Read every status against the table and ask what the file is waiting for whenever the answer is vague. Note the dates that matter, because IRDAI now expects a surveyor within 24 hours, a final report within 15 days and a decision within 7 days of that report. If those limits slip, the grievance officer, Bima Bharosa and the Ombudsman are there, in that order, at no cost to you. Above all, respond to insurer queries the same day, since your own promptness is the one factor entirely in your hands.
Disclaimer: The information provided on this platform is intended for general awareness and educational purposes. While every effort is made to ensure accuracy, some details may change with policy updates, regulatory revisions, or insurer-specific modifications. Readers should verify current terms and conditions directly with relevant insurers or through professional consultation before making any decision.
All views and analyses presented are based on publicly available data, internal research and other sources considered reliable at the time of writing. These do not constitute professional advice, recommendations, or guarantees of any product’s performance. Readers are encouraged to assess the information independently and seek qualified guidance suited to their individual requirements. Customers are advised to review official sales brochures, policy documents and disclosures before proceeding with any purchase or commitment.
FAQs
Some insurers let you search with the vehicle registration number alone on their claim-status page, usually followed by an OTP to the mobile registered with the policy. Others insist on the claim number or policy number instead. Enter the registration exactly as printed on the RC, without spaces and watch for an O typed in place of a zero. If the page returns nothing, customer care can locate the file using your policy number and accident date.
Yes, though it takes an extra step. Search your SMS, email and spam folder for the intimation message, since the number is sent at registration. Failing that, call customer care with your policy number, vehicle number and incident date and ask for the claim number to be read back or resent. For a cashless claim, the network garage will also have it on its approval request.
Under IRDAI's 2024 master circular, the surveyor is allotted within 24 hours, the final report is due within 15 days of appointment and the insurer must decide within 7 days of receiving it. That adds up to roughly 23 days from reporting to a decision. Missing documents, revised estimates and parts delays at the garage can stretch actual repairs and theft or total-loss claims typically take longer.
It usually means the file is waiting on someone, whether that is the surveyor's report, an estimate approval or a reply from you. Ask customer care which specific item is pending and since when and check the app for open document requests. If the survey report has been in for more than 7 days without a decision, cite the IRDAI timeline in writing.
Yes and it is often the quickest source. The garage sends the repair estimate and any supplementary estimate to the insurer, so its service advisor knows when approval arrives. Ask for updates in writing or by message so you have a record and cross-check with the insurer's app if the two versions differ.
For motor losses above Rs. 50,000, IRDAI requires assessment by a registered surveyor. Smaller claims may be settled without a physical survey, sometimes through self-inspection on the insurer's app, depending on the insurer's claims policy. Avoid starting repairs before the insurer or surveyor clears them, unless the car is unsafe, since that can complicate the assessment.
Begin with the insurer's grievance redressal officer, then register on Bima Bharosa or call 155255 if the reply is late or unsatisfactory. The Insurance Ombudsman is the next step and you can approach it after an unsatisfactory reply or a month of silence from the insurer, within one year. All three routes are free.


