


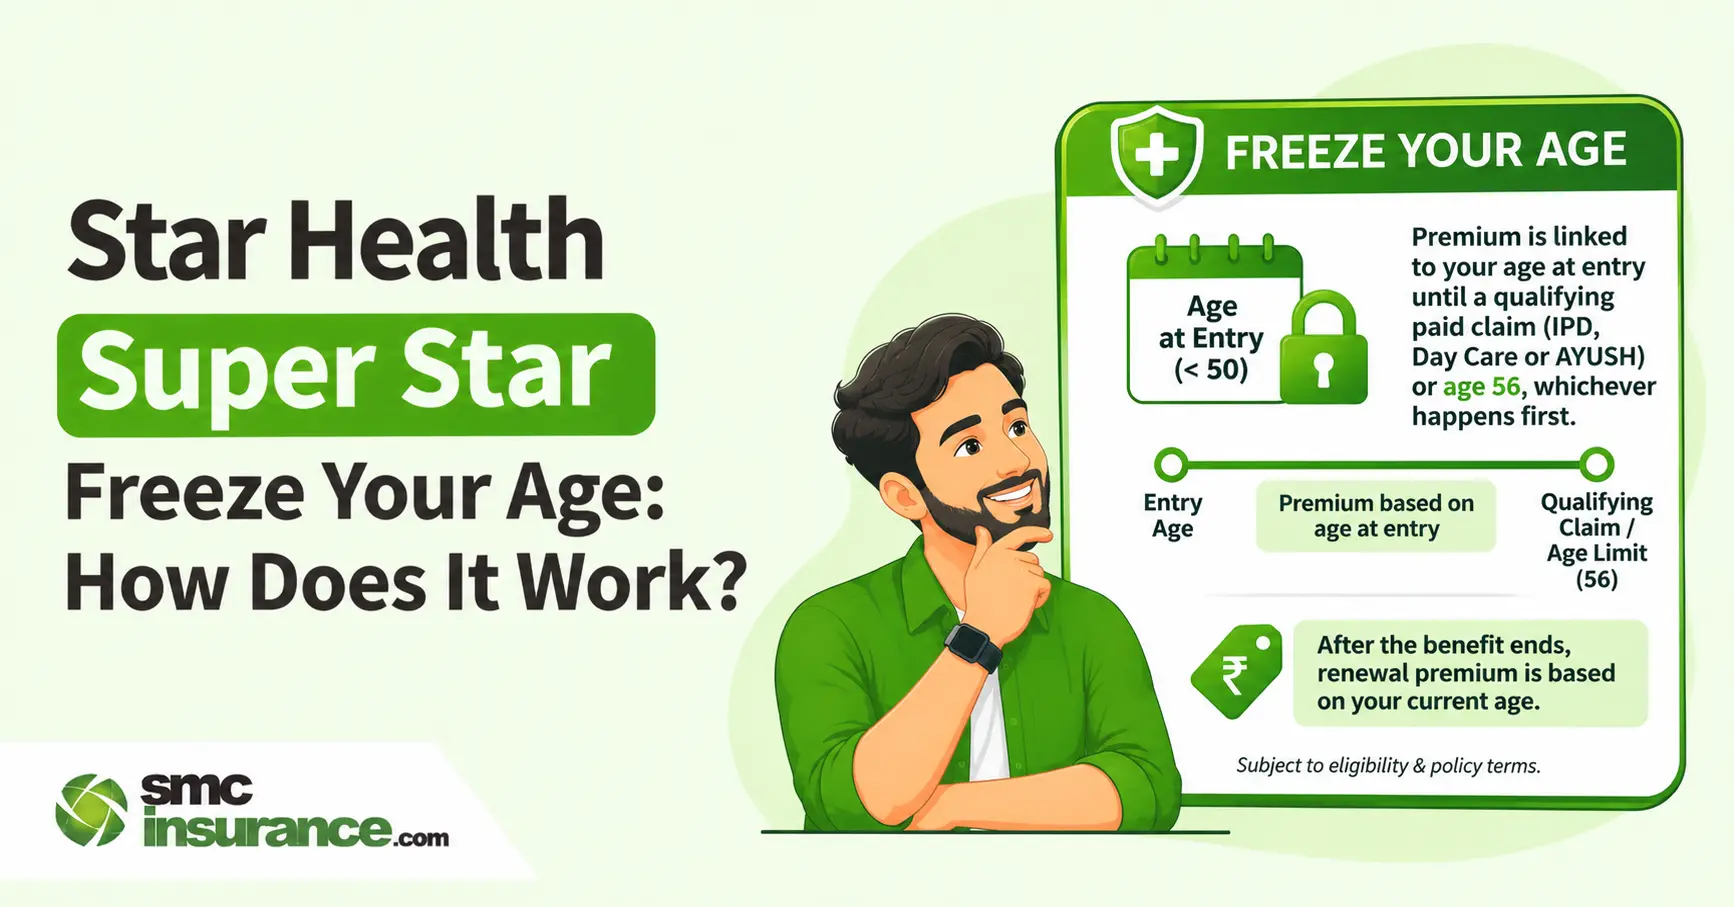
Star Health Super Star's Freeze Your Age benefit keeps the age used for premium calculation fixed at your entry age if you join at 50 or younger. It continues until a claim is incurred under the basic inpatient, day care or AYUSH treatment cover, or until you turn 56, whichever happens first. Thereafter, premiums are calculated using your actual age at renewal. The benefit does not prevent other premium revisions.
Table of Contents
Premiums on a health policy rarely stay where you first found them and most people notice the climb only when a renewal notice arrives at 45 with a number nobody warned them about. Star Health’s Super Star Plan tackles that with a feature called Freeze Your Age, which prices your renewals on the age you joined rather than the age you have reached. It sounds like a simple lock, yet the fine print on when it ends decides whether it saves you money. Here is how the Star Health Super Star Freeze Your Age benefit works, where it stops and who should care.
How Freeze Your Age Works in the Super Star Plan
The idea is simpler than the marketing makes it sound, so start with the mechanics.
Insurers price health cover by age band, so a 38-year-old pays more than a 33-year-old for identical benefits. Under this feature, Star Health keeps using your entry age at every renewal, so your band stays put.
Point |
What Star Health states |
Who gets it | Insured members entering at age 50 or younger |
What is frozen | Entry age used for renewal premium calculations |
What ends it | A claim under the basic inpatient, day care or AYUSH cover, or attaining age 56 |
Age cap | 56 years under the 2026 policy wording |
Afterwards | Premium calculated using actual age at renewal |
Note: Star Health's product highlights mention age 55, but Clause 19 of its 2026 Super Star policy wording specifies age 56. The contractual wording should be referred to when confirming the benefit's expiry.
When the Freeze Ends: Super Star Premium After Your First Claim
The first paid claim is the real switch and it behaves differently depending on how you bought the policy.
Suppose you buy at 35 and stay claim-free, so you keep paying as a 35-year-old. If a hospital claim is paid at 42, the next renewal is priced on your age then and every renewal after that moves with you.
Policy type |
Effect of a paid claim |
Individual | Unlocks your age |
Floater | Any member’s claim unlocks age for all insured members |
Multi-individual | Unlocks only for the member who claimed |
Note: Your policy schedule governs.
A family with young children, where a claim is likelier in any given year, may see the lock end sooner than a single adult’s would.
Does Freezing Your Age Really Lower Your Health Insurance Premium?
Not quite and this is where most buyers misread it.
A frozen age is not a frozen price. Star Health states that renewal premiums remain subject to change under prevailing guidelines, so repricing and medical inflation can still lift your bill. What you avoid is the extra step up from moving into an older age band.
The feature pairs well with other levers on the same policy. A five-year term earns discounts of 10%, 12.5%, 14% and 16% on the second to fifth year premiums, early renewal earns 2.5% and wellness points can cut renewal premiums by up to 20%. Choosing the Unlimited sum insured, however, rules out the Super Star Bonus and Limitless Care covers. Our explainer on restoration versus no-claim bonus shows how that trade works.
Wondering whether a locked age beats a cheaper plan with a bigger cover? An SMC Insurance advisor can put both quotes side by side at SMC Insurance before you pay anything.
Who Should Buy Super Star for the Freeze Your Age Benefit
A good fit is someone in their thirties or early forties, healthy today, who expects to stay with one insurer for a decade or more.
It suits poorly if you expect hospital visits soon, since one claim ends the lock. Waiting periods also stay in force, with 36 months for pre-existing diseases and 24 months for specified conditions, as our guide to pre-existing disease waiting periods explains. The optional Quick Shield cover waives the wait for diabetes, hypertension, asthma, high cholesterol and certain heart conditions from day 31 and it helps to know how waiting periods differ before you choose.
Wrapping Up
Freeze Your Age rewards one thing, which is staying claim-free for a long stretch after buying young. If that describes you, the lock keeps age-driven increases out of your renewals for years, though medical inflation will still show up. If you expect early claims, judge the plan on its cover alone. Read the policy clause for the exact age cap and confirm you enter below 50.
Disclaimer: The information provided on this platform is intended for general awareness and educational purposes. While every effort is made to ensure accuracy, some details may change with policy updates, regulatory revisions, or insurer-specific modifications. Readers should verify current terms and conditions directly with relevant insurers or through professional consultation before making any decision.
All views and analyses presented are based on publicly available data, internal research and other sources considered reliable at the time of writing. These do not constitute professional advice, recommendations, or guarantees of any product’s performance. Readers are encouraged to assess the information independently and seek qualified guidance suited to their individual requirements. Customers are advised to review official sales brochures, policy documents and disclosures before proceeding with any purchase or commitment.
FAQs
It keeps your renewal premium priced on your entry age until your first paid in-patient, day care or AYUSH claim, or until the age cap, after which your actual age applies.
Under Star Health's 2026 Super Star policy wording, Freeze Your Age continues until the insured turns 56 or incurs a qualifying claim, whichever occurs earlier. Although the insurer's product highlights mention 55, Clause 19 of the policy wording specifies 56.
Not necessarily. Only the age used for pricing is frozen, so medical inflation or repricing can still raise the amount at renewal.
Yes, on a floater, a paid claim by any insured member unlocks the age for everyone covered, whereas on a multi-individual policy only the claimant loses the lock.
The benefit is offered to buyers entering below 50, so late entrants should not count on it. Premiums then follow their attained age.


